Jean Jacod – författare
Visar alla böcker från författaren Jean Jacod. Handla med fri frakt och snabb leverans.
17 produkter
High-Frequency Financial Econometrics
Av Yacine Aït-Sahalia, Jean Jacod
Inbunden, 2014
641 kr
Lägg i varukorg
High-frequency trading is an algorithm-based computerized trading practice that allows firms to trade stocks in milliseconds. Over the last fifteen years, the use of statistical and econometric methods for analyzing high-frequency financial data has grown exponentially. This growth has been driven …
High-Frequency Financial Econometrics
Av Jean Jacod, Yacine Ait-Sahalia
E-bok, 2014
881 kr
Lägg i varukorg
A comprehensive introduction to the statistical and econometric methods for analyzing high-frequency financial data High-frequency trading is an algorithm-based computerized trading practice that allows firms to trade stocks in milliseconds. Over the last fifteen years, the use of statistical and …
Ecole d'Ete de Probabilites de Saint-Flour XIII, 1983
Av David J. Aldous, Illdar A. Ibragimov m. fl.
Häftad, 1985
496 kr
Lägg i varukorg
Ecole d'Ete de Probabilites de Saint-Flour XIII, 1983
Av Jean Jacod, Illdar A. Ibragimov m. fl.
E-bok, 2006
440 kr
Lägg i varukorg
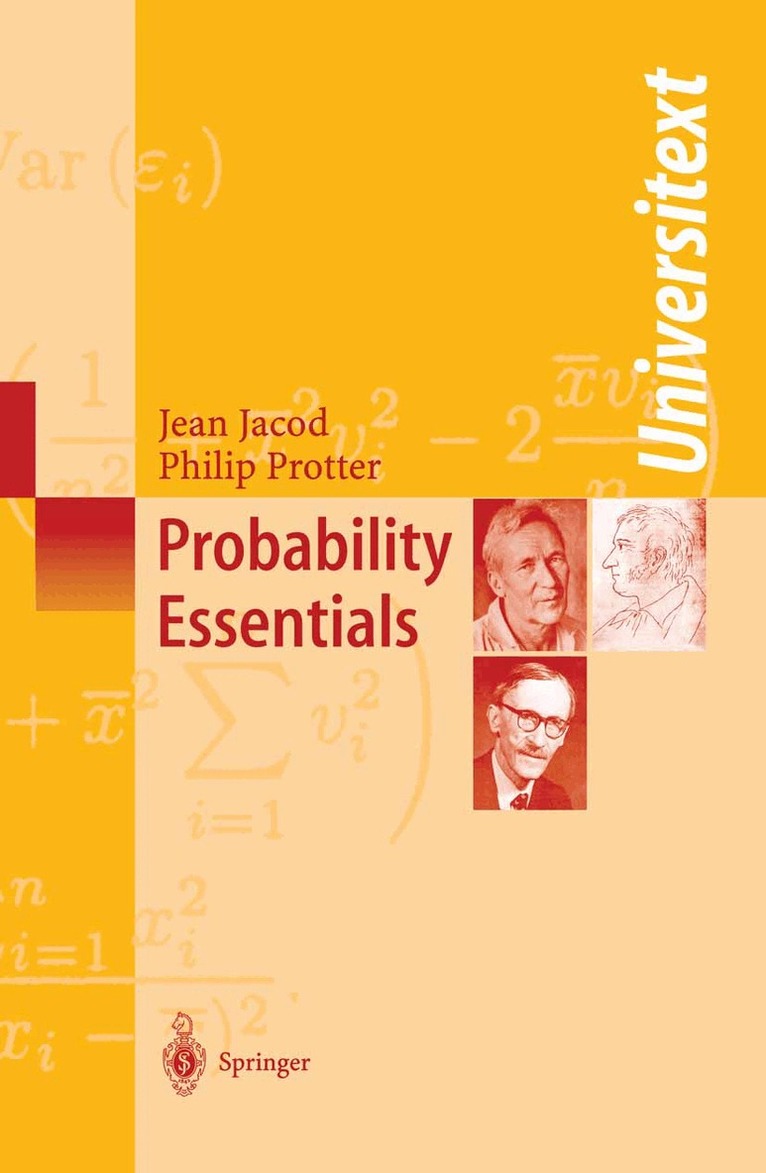
Probability Essentials
Häftad, 2002
769 kr
Lägg i varukorg
We present here a one semester course on Probability Theory. We also treat measure theory and Lebesgue integration, concentrating on those aspects which are especially germane to the study of Probability Theory. The book is intended to fill a current need: there are mathematically sophisticated …
Limit Theorems for Stochastic Processes
Av Jean Jacod, Albert Shiryaev
Inbunden, 2002
1861 kr
Lägg i varukorg
Initially the theory of convergence in law of stochastic processes was developed quite independently from the theory of martingales, semimartingales and stochastic integrals. Apart from a few exceptions essentially concerning diffusion processes, it is only recently that the relation between the …
Limit Theorems for Stochastic Processes
Av Jean Jacod, Albert Shiryaev
Häftad, 2010
1861 kr
Lägg i varukorg
Initially the theory of convergence in law of stochastic processes was developed quite independently from the theory of martingales, semimartingales and stochastic integrals. Apart from a few exceptions essentially concerning diffusion processes, it is only recently that the relation between the …
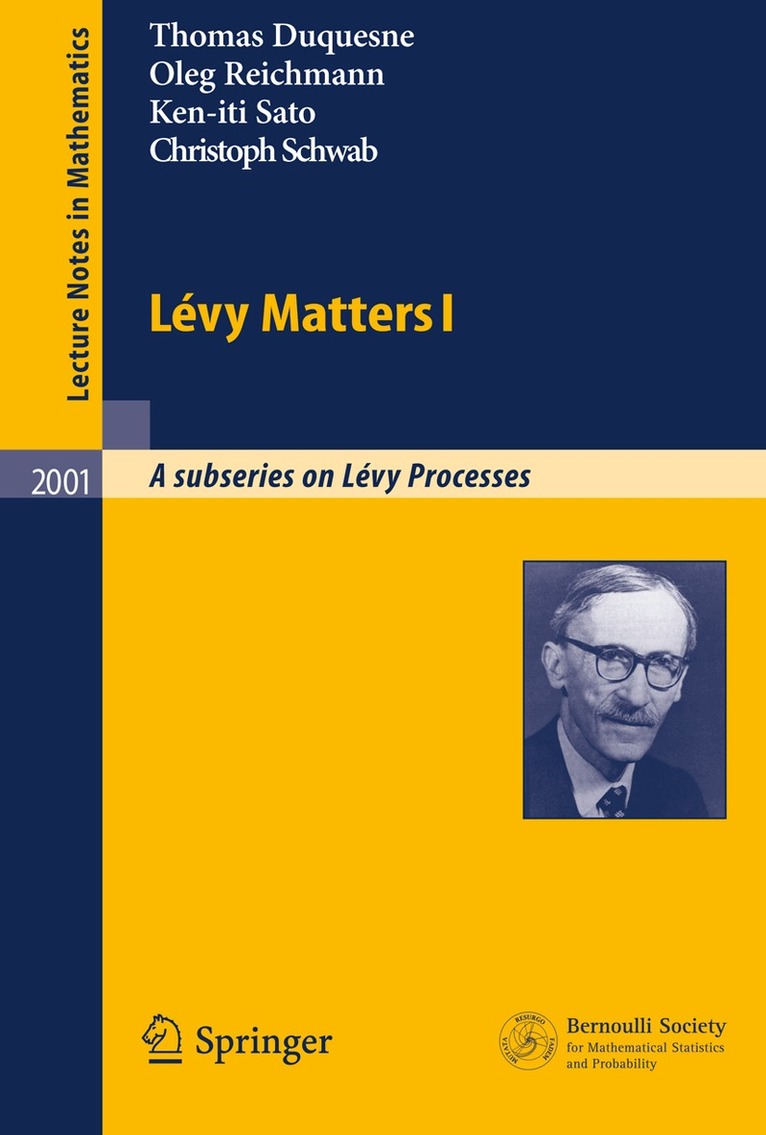
Lévy Matters I
Recent Progress in Theory and Applications: Foundations, Trees and Numerical Issues in Finance
Av Thomas Duquesne, Oleg Reichmann m. fl.
Häftad, 2010
551 kr
Lägg i varukorg
Over the past 10-15 years, we have seen a revival of general Levy ' processes theory as well as a burst of new applications. In the past, Brownian motion or the Poisson process have been considered as appropriate models for most applications. Nowadays, the need for more realistic modelling of …
Levy Matters I
Recent Progress in Theory and Applications: Foundations, Trees and Numerical Issues in Finance
Av Christoph Schwab, Ken-iti Sato m. fl.
E-bok, 2010
718 kr
Lägg i varukorg
Discretization of Processes
Inbunden, 2011
1643 kr
Lägg i varukorg
In applications, and especially in mathematical finance, random time-dependent events are often modeled as stochastic processes. Assumptions are made about the structure of such processes, and serious researchers will want to justify those assumptions through the use of data. As statisticians are …
Discretization of Processes
E-bok, 2011
2065 kr
Lägg i varukorg
In applications, and especially in mathematical finance, random time-dependent events are often modeled as stochastic processes. Assumptions are made about the structure of such processes, and serious researchers will want to justify those assumptions through the use of data. As statisticians are …
Lévy Processes at Saint-Flour
Av Jean Bertoin, Jean L. Bretagnolle m. fl.
Häftad, 2012
551 kr
Lägg i varukorg
Bretagnolle, Jean: Processus a accroissements indépendants.- Ibragimov, Ildar: Théorèmes limites pour les marches aléatoires.- Jacod, Jean: Théorèmes limite pour les processus.- Bertoin, Jean: Subordinators: Examples and applications.- Doney, Ronald A.: Fluctuation theory for Lévy processes.
Discretization of Processes
Häftad, 2013
1643 kr
Lägg i varukorg
In applications, and especially in mathematical finance, random time-dependent events are often modeled as stochastic processes. Assumptions are made about the structure of such processes, and serious researchers will want to justify those assumptions through the use of data. As statisticians are …
Probability Essentials
E-bok, 2012
1174 kr
Lägg i varukorg
We present here a one-semester course on Probability Theory. We also treat measure theory and Lebesgue integration, concentrating on those aspects which are especially germane to the study of Probability Theory. The book is intended to fill a current need: there are mathematically sophisticated …
Probability Essentials
E-bok, 2012
897 kr
Lägg i varukorg
We present here a one semester course on Probability Theory. We also treat measure theory and Lebesgue integration, concentrating on those aspects which are especially germane to the study of Probability Theory. The book is intended to fill a current need: there are mathematically sophisticated …
Limit Theorems for Stochastic Processes
Av Albert N. Shiryaev, Jean Jacod
E-bok, 2013
1174 kr
Lägg i varukorg
Initially the theory of convergence in law of stochastic processes was developed quite independently from the theory of martingales, semimartingales and stochastic integrals. Apart from a few exceptions essentially concerning diffusion processes, it is only recently that the relation between the …
Limit Theorems for Stochastic Processes
Av Albert Shiryaev, Jean Jacod
E-bok, 2013
2437 kr
Lägg i varukorg
Initially the theory of convergence in law of stochastic processes was developed quite independently from the theory of martingales, semimartingales and stochastic integrals. Apart from a few exceptions essentially concerning diffusion processes, it is only recently that the relation between the …