
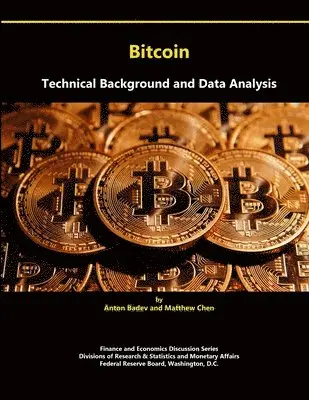
Bitcoin: Technical Background and Data Analysis
Federal Reserve Board, Matthew Chen, Anton Badev
Häftad, 2015
186 kr
230 kr
Beställningsvara. Skickas inom 3-6 vardagar. Fri frakt över 249 kr.
Federal Reserve Board, Matthew Chen, Anton Badev
Häftad, 2015
186 kr
230 kr
Beställningsvara. Skickas inom 3-6 vardagar. Fri frakt över 249 kr.
Federal Reserve Board, Matthew Chen, Anton Badev
Häftad, 2015
186 kr
230 kr
Beställningsvara. Skickas inom 3-6 vardagar. Fri frakt över 249 kr.
Federal Reserve Board, Matthew Chen, Anton Badev
Häftad, 2015
186 kr