• Fri frakt över 249 kr
  • •
  • Snabba leveranser
  • •
  • Billiga böcker
Kundservice

Du är på sajten för privatpersoner.

Företag, bibliotek eller offentlig verksamhet?

Du handlar på classic.bokus.com, där alla dina funktioner finns intakta.
Till classic.bokus.com
Bokus logotyp. Gå till startsidan.
  • Erbjudanden
  • Nyheter
  • Student
  • Topplistor
  • Barn & ungdom
  • Bokus Play
  • E-böcker
  • Pocketböcker
  • Spel & pussel

Upp till 20% på populära nyheter →

Sidfot

Mina sidor

    Hjälp

    • Kundservice
    • Vanliga frågor och svar
    • Frakt och leverans
    • Retur vid ångerrätt
    • Reklamera vara
    • Betalning
    • Köpvillkor
    • Allmänna villkor
    • Information om webbplatsens tillgänglighet

    Om Bokus

    • Om oss
    • Pressrum
    • För studenter
    • För företag
    • För bibliotek och offentlig verksamhet
    • För leverantörer
    • Hållbarhet

    Populärt

    • Aktuella erbjudanden
    • Presentkort
    • Studentlitteratur
    • Nya böcker
    • Topplistor
    • Signerade böcker
    • Engelska böcker

    Inspiration

    • Boktips
    • BookTok
    • Populära bokserier
    • Barnbokskaraktärer
    • Populära författare

    Mina sidor

      Hjälp

      • Kundservice
      • Vanliga frågor och svar
      • Frakt och leverans
      • Retur vid ångerrätt
      • Reklamera vara
      • Betalning
      • Köpvillkor
      • Allmänna villkor
      • Information om webbplatsens tillgänglighet

      Om Bokus

      • Om oss
      • Pressrum
      • För studenter
      • För företag
      • För bibliotek och offentlig verksamhet
      • För leverantörer
      • Hållbarhet

      Populärt

      • Aktuella erbjudanden
      • Presentkort
      • Studentlitteratur
      • Nya böcker
      • Topplistor
      • Signerade böcker
      • Engelska böcker

      Inspiration

      • Boktips
      • BookTok
      • Populära bokserier
      • Barnbokskaraktärer
      • Populära författare
      Logotyp för Bokus
      Följ oss på Facebook (extern länk)Följ oss på Instagram (extern länk)Följ oss på YouTube (extern länk)Följ oss på TikTok (extern länk)
      bokus @ CookiesIntegritetspolicyKöpvillkor
      Till Citymail hemsida (extern länk)Till Budbee hemsida (extern länk)Till Postnord hemsida (extern länk)Till Schenker hemsida (extern länk)Till Early Bird hemsida (extern länk)Till Walleys hemsida (extern länk)
      1. Ekonomi och Ledarskap
      2. Nationalekonomi
      3. Mikroekonomi

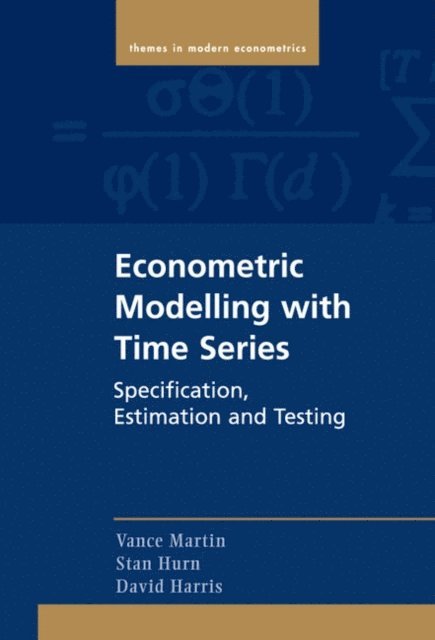
      Econometric Modelling with Time Series

      Specification, Estimation and Testing

      AvVance Martin,Stan Hurn

      Häftad, Engelska, 2012

      Del i serien Themes in Modern Econometrics

      1 080 kr

      Beställningsvara. Skickas inom 5-8 vardagar. Fri frakt över 249 kr.
      Fler format och utgåvor

      Inbunden

      1 506 kr

      Beskrivning

      This book provides a general framework for specifying, estimating and testing time series econometric models. Special emphasis is given to estimation by maximum likelihood, but other methods are also discussed, including quasi-maximum likelihood estimation, generalised method of moments estimation, nonparametric estimation and estimation by simulation. An important advantage of adopting the principle of maximum likelihood as the unifying framework for the book is that many of the estimators and test statistics proposed in econometrics can be derived within a likelihood framework, thereby providing a coherent vehicle for understanding their properties and interrelationships. In contrast to many existing econometric textbooks, which deal mainly with the theoretical properties of estimators and test statistics through a theorem-proof presentation, this book squarely addresses implementation to provide direct conduits between the theory and applied work.

      Produktinformation

      • Utgivningsdatum:2012-12-28
      • Mått:152 x 226 x 48 mm
      • Vikt:1 180 g
      • Format:Häftad
      • Språk:Engelska
      • Serie:Themes in Modern Econometrics
      • Antal sidor:924
      • Förlag:Cambridge University Press
      • ISBN:9780521139816

      Utforska kategorier

      • Mikroekonomi inom Ekonomi och Ledarskap

      Mer om författaren

      Vance Martin is Professor of Econometrics at the University of Melbourne, Australia, a position he has held since 2000. He graduated with a PhD from Monash University in 1990. He was appointed Lecturer at the University of Melbourne in 1985 and became a Senior Lecturer in 1990. Stan Hurn is Professor of Economics and Finance at Queensland University of Technology, Australia, a position he has held since 1998. He graduated with a DPhil in Economics from St Edmund Hall, Oxford, in 1992. He was appointed Lecturer at the University of Glasgow in 1988 and became a Senior Lecturer in 1993 before being named Official Fellow in Economics at Brasenose College, Oxford, in 1996. David Harris is Professor of Econometrics at Monash University, Australia. He was awarded his PhD in Econometrics from Monash University in 1995. He was lecturer in econometrics from 1995 to 1997 at Monash University and from 1998 to 2010 at the University of Melbourne.

      Recensioner i media

      'This book will be an excellent text for advanced undergraduate and postgraduate courses in econometric time series. The statistical theory is clearly presented and the many examples make the techniques readily accessible and illustrate their practical importance.' Andrew Harvey, University of Cambridge

      Innehållsförteckning

      • Part I. Maximum Likelihood: 1. The maximum likelihood principle; 2. Properties of maximum likelihood estimators; 3. Numerical estimation methods; 4. Hypothesis testing; Part II. Regression Models: 5. Linear regression models; 6. Nonlinear regression models; 7. Autocorrelated regression models; 8. Heteroskedastic regression models; Part III. Other Estimation Methods: 9. Quasi-maximum likelihood estimation; 10. Generalized method of moments; 11. Nonparametric estimation; 12. Estimation by stimulation; Part IV. Stationary Time Series: 13. Linear time series models; 14. Structural vector autoregressions; 15. Latent factor models; Part V. Non-Stationary Time Series: 16. Nonstationary distribution theory; 17. Unit root testing; 18. Cointegration; Part VI. Nonlinear Time Series: 19. Nonlinearities in mean; 20. Nonlinearities in variance; 21. Discrete time series models; Appendix A. Change in variable in probability density functions; Appendix B. The lag operator; Appendix C. FIML estimation of a structural model; Appendix D. Additional nonparametric results.
      Hoppa över listan

      Mer från samma författare

      David Harris, Stan Hurn, Vance Martin - Econometric Modelling with Time Series, E-bok

      Econometric Modelling with Time Series

      David Harris, Stan Hurn, Vance Martin

      E-bok
      2012

      1 281 kr

      David Harris, Stan Hurn, Vance Martin - Econometric Modelling with Time Series, E-bok

      Econometric Modelling with Time Series

      David Harris, Stan Hurn, Vance Martin

      E-bok
      2012

      1 268 kr

      Hoppa över listan

      Mer från samma serie

      Adonis Yatchew - Semiparametric Regression for the Applied Econometrician, Häftad

      Semiparametric Regression for the Applied Econometrician

      Adonis Yatchew

      Häftad, 2003

      448 kr

      Christian Gourieroux, Peter C. B. Phillips, Christian Gourieroux - Econometrics of Qualitative Dependent Variables, Inbunden

      Econometrics of Qualitative Dependent Variables

      Christian Gourieroux, Peter C. B. Phillips, Christian Gourieroux

      Inbunden, 2000

      1 300 kr
      Adrian Pagan, Aman Ullah, Peter C. B. Phillips - Nonparametric Econometrics, Inbunden

      Nonparametric Econometrics

      Adrian Pagan, Aman Ullah, Peter C. B. Phillips

      Inbunden, 1999

      1 389 kr

      Christian Gourieroux, Alain Monfort - Statistics and Econometric Models: Volume 1, General Concepts, Estimation, Prediction and Algorithms, Inbunden

      Statistics and Econometric Models: Volume 1, General Concepts, Estimation, Prediction and Algorithms

      Christian Gourieroux, Alain Monfort

      Inbunden, 1995

      2 212 kr
      Christian Gourieroux, Alain Monfort - Time Series and Dynamic Models, Inbunden

      Time Series and Dynamic Models

      Christian Gourieroux, Alain Monfort

      Inbunden, 1996

      2 296 kr

      Christian Gourieroux, Alain Monfort - Time Series and Dynamic Models, Häftad

      Time Series and Dynamic Models

      Christian Gourieroux, Alain Monfort

      Häftad, 1997

      705 kr

      Christian Gourieroux, Alain Monfort - Statistics and Econometric Models: Volume 2, Testing, Confidence Regions, Model Selection and Asymptotic Theory, Inbunden

      Statistics and Econometric Models: Volume 2, Testing, Confidence Regions, Model Selection and Asymptotic Theory

      Christian Gourieroux, Alain Monfort

      Inbunden, 1995

      2 017 kr
      Christian Gourieroux, Alain Monfort, Alain Monfort, Peter C. B. Phillips - Statistics and Econometric Models, Häftad

      Statistics and Econometric Models

      Christian Gourieroux, Alain Monfort, Alain Monfort, Peter C. B. Phillips

      Häftad, 1995

      594 kr
      Christian Gourieroux, Alain Monfort, Christain Gourieroux, Peter C. B. Phillips - Statistics and Econometric Models, Häftad

      Statistics and Econometric Models

      Christian Gourieroux, Alain Monfort, Christain Gourieroux, Peter C. B. Phillips

      Häftad, 1995

      594 kr
      Herman J. Bierens, Peter C. B. Phillips, Christian Gourieroux - Introduction to the Mathematical and Statistical Foundations of Econometrics, Häftad

      Introduction to the Mathematical and Statistical Foundations of Econometrics

      Herman J. Bierens, Peter C. B. Phillips, Christian Gourieroux

      Häftad, 2004

      612 kr
      Hoppa över listan

      Du kanske också är intresserad av

      Vance Martin, Stan Hurn, David Harris - Econometric Modelling with Time Series, Inbunden

      Econometric Modelling with Time Series

      Vance Martin, Stan Hurn, David Harris

      Inbunden, 2012

      1 506 kr

      David Harris, Stan Hurn, Vance Martin - Econometric Modelling with Time Series, E-bok

      Econometric Modelling with Time Series

      David Harris, Stan Hurn, Vance Martin

      E-bok
      2012

      1 268 kr

      David Harris, Stan Hurn, Vance Martin - Econometric Modelling with Time Series, E-bok

      Econometric Modelling with Time Series

      David Harris, Stan Hurn, Vance Martin

      E-bok
      2012

      1 281 kr

      Stan Hurn, Vance L. Martin, Jun Yu, Peter C.B. Phillips - Financial Econometric Modeling, Häftad

      Financial Econometric Modeling

      Stan Hurn, Vance L. Martin, Jun Yu, Peter C.B. Phillips

      Häftad, 2020

      1 476 kr
      Ralf Becker, Stan Hurn - Contemporary Issues in Economics and Econometrics, Inbunden

      Contemporary Issues in Economics and Econometrics

      Ralf Becker, Stan Hurn

      Inbunden, 2004

      1 957 kr

      Eric Ghysels, Denise R. Osborn - The Econometric Analysis of Seasonal Time Series, Häftad

      The Econometric Analysis of Seasonal Time Series

      Eric Ghysels, Denise R. Osborn

      Häftad, 2001

      594 kr

      Eric Ghysels, Denise R. Osborn - The Econometric Analysis of Seasonal Time Series, Inbunden

      The Econometric Analysis of Seasonal Time Series

      Eric Ghysels, Denise R. Osborn

      Inbunden, 2001

      1 444 kr
      Christian Gourieroux, Alain Monfort - Time Series and Dynamic Models, Inbunden

      Time Series and Dynamic Models

      Christian Gourieroux, Alain Monfort

      Inbunden, 1996

      2 296 kr

      Shuping Shi, Xiaohu Wang, Tao Zeng - Financial Econometrics, Inbunden

      Financial Econometrics

      Shuping Shi, Xiaohu Wang, Tao Zeng

      Inbunden, 2025

      1 403 kr

      G. S. Maddala, In-Moo Kim - Unit Roots, Cointegration, and Structural Change, Häftad

      Unit Roots, Cointegration, and Structural Change

      G. S. Maddala, In-Moo Kim

      Häftad, 1999

      594 kr