Inbunden, Engelska, 2026
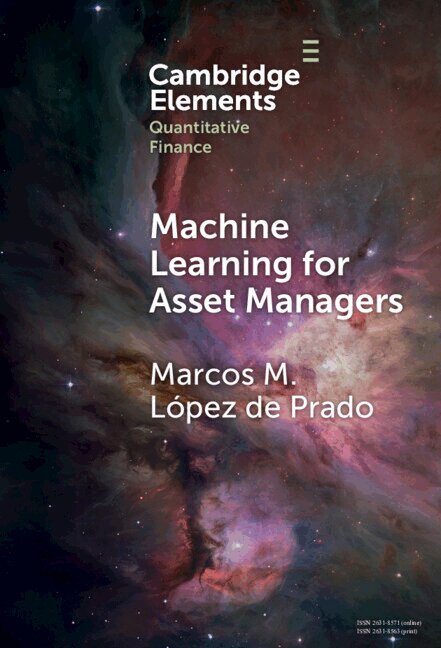
Machine Learning for Asset Managers
Av Marcos M. López de Prado
930 kr
Skickas torsdag 15/10. Fri frakt över 249 kr.
Beskrivning
Successful investment strategies are specific implementations of general theories. An investment strategy that lacks a theoretical justification is likely to be false. Hence, an asset manager should concentrate her efforts on developing a theory rather than on backtesting potential trading rules. The purpose of this Element is to introduce machine learning (ML) tools that can help asset managers discover economic and financial theories. ML is not a black box, and it does not necessarily overfit. ML tools complement rather than replace the classical statistical methods. Some of ML's strengths include (1) a focus on out-of-sample predictability over variance adjudication; (2) the use of computational methods to avoid relying on (potentially unrealistic) assumptions; (3) the ability to "learn" complex specifications, including nonlinear, hierarchical, and noncontinuous interaction effects in a high-dimensional space; and (4) the ability to disentangle the variable search from the specification search, robust to multicollinearity and other substitution effects.
Produktinformation
- Utgivningsdatum: 2026-01-08
- Mått: 152 x 229 x 10 mm
- Vikt: 365 g
- Format: Inbunden
- Språk: Engelska
- Serie: Elements in Quantitative Finance
- Antal sidor: 152
- Förlag: Cambridge University Press
- ISBN: 9781009702423
Utforska kategorier
Betyg & recensioner
0 recensioner
Inga recensioner tillgängliga.