Giulia Di Nunno – författare
Visar alla böcker från författaren Giulia Di Nunno. Handla med fri frakt och snabb leverans.
11 produkter
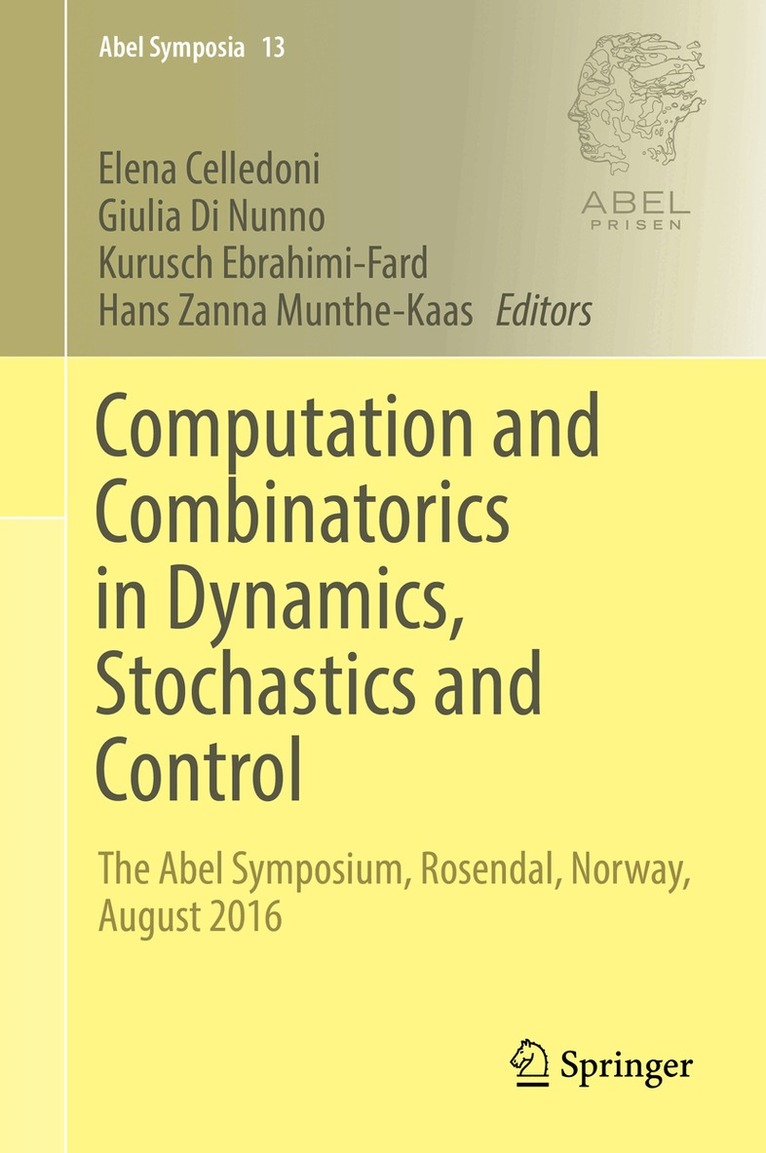
Computation and Combinatorics in Dynamics, Stochastics and Control
The Abel Symposium, Rosendal, Norway, August 2016
Av Elena Celledoni, Giulia Di Nunno m. fl.
Inbunden, 2019
1853 kr
Lägg i varukorg
The Abel Symposia volume at hand contains a collection of high-quality articles written by the world’s leading experts, and addressing all mathematicians interested in advances in deterministic and stochastic dynamical systems, numerical analysis, and control theory.In recent years we have …
Computation and Combinatorics in Dynamics, Stochastics and Control
The Abel Symposium, Rosendal, Norway, August 2016
Av Hans Zanna Munthe-Kaas, Kurusch Ebrahimi-Fard m. fl.
E-bok, 2019
2437 kr
Lägg i varukorg
The Abel Symposia volume at hand contains a collection of high-quality articles written by the world’s leading experts, and addressing all mathematicians interested in advances in deterministic and stochastic dynamical systems, numerical analysis, and control theory. In recent years we have …
Volterra Volatility Models
Option Pricing and Hedging
Av Giulia Di Nunno, Yuliya Mishura m. fl.
Inbunden, 2026
1749 kr
Lägg i varukorg
Financial markets have extremely complex behavior that cannot be fully modeled using classical approaches. In particular, numerous empirical studies show that market volatility exhibits some form of long-range dependence and has time-varying Hölder regularity with prominent periods of “roughness” …
Volterra Volatility Models
Option Pricing and Hedging
Av Anton Yurchenko-Tytarenko, Yuliya Mishura m. fl.
E-bok, 2026
2224 kr
Lägg i varukorg
Financial markets have extremely complex behavior that cannot be fully modeled using classical approaches. In particular, numerous empirical studies show that market volatility exhibits some form of long-range dependence and has time-varying Hölder regularity with prominent periods of “roughness” …
Stochastics of Environmental and Financial Economics
Centre of Advanced Study, Oslo, Norway, 2014-2015
Av Fred Espen Benth, Giulia Di Nunno
Inbunden, 2015
550 kr
Lägg i varukorg
These Proceedings offer a selection of peer-reviewed research and survey papers by some of the foremost international researchers in the fields of finance, energy, stochastics and risk, who present their latest findings on topical problems. The papers cover the areas of stochastic modeling in …
Stochastics of Environmental and Financial Economics
Centre of Advanced Study, Oslo, Norway, 2014-2015
Av Fred Espen Benth, Giulia Di Nunno
Häftad, 2016
550 kr
Lägg i varukorg
These Proceedings offer a selection of peer-reviewed research and survey papers by some of the foremost international researchers in the fields of finance, energy, stochastics and risk, who present their latest findings on topical problems. The papers cover the areas of stochastic modeling in …
Stochastic Analysis and Applications
The Abel Symposium 2005
Av Fred Espen Benth, Giulia Di Nunno m. fl.
Inbunden, 2007
1636 kr
Lägg i varukorg
Kiyosi Ito, the founder of stochastic calculus, is one of the few central figures of the twentieth century mathematics who reshaped the mathematical world. Today stochastic calculus is a central research field with applications in several other mathematical disciplines, for example physics, …
Stochastic Analysis and Applications
The Abel Symposium 2005
Av Tusheng Zhang, Bernt oksendal m. fl.
E-bok, 2007
2049 kr
Lägg i varukorg
Kiyosi Ito, the founder of stochastic calculus, is one of the few central figures of the twentieth century mathematics who reshaped the mathematical world. Today stochastic calculus is a central research field with applications in several other mathematical disciplines, for example physics, …
Malliavin Calculus for Lévy Processes with Applications to Finance
Av Giulia Di Nunno, Bernt Øksendal m. fl.
Häftad, 2008
5,0 utav 5 stjärnor. Totalt antal röster: (1)
876 kr
Lägg i varukorg
There are already several excellent books on Malliavin calculus. However, most of them deal only with the theory of Malliavin calculus for Brownian motion, with [35] as an honorable exception. Moreover, most of them discuss only the applicationto regularityresults for solutions ofSDEs, as this …
Malliavin Calculus for Levy Processes with Applications to Finance
Av Frank Proske, Bernt oksendal m. fl.
E-bok, 2008
1059 kr
Lägg i varukorg
Stochastic Analysis and Applications
The Abel Symposium 2005
Av Fred Espen Benth, Giulia Di Nunno m. fl.
Häftad, 2010
1636 kr
Lägg i varukorg
Kiyosi Ito, the founder of stochastic calculus, is one of the few central figures of the twentieth century mathematics who reshaped the mathematical world. Today stochastic calculus is a central research field with applications in several other mathematical disciplines, for example physics, …