Marek Capiński – författare
Visar alla böcker från författaren Marek Capiński. Handla med fri frakt och snabb leverans.
8 produkter
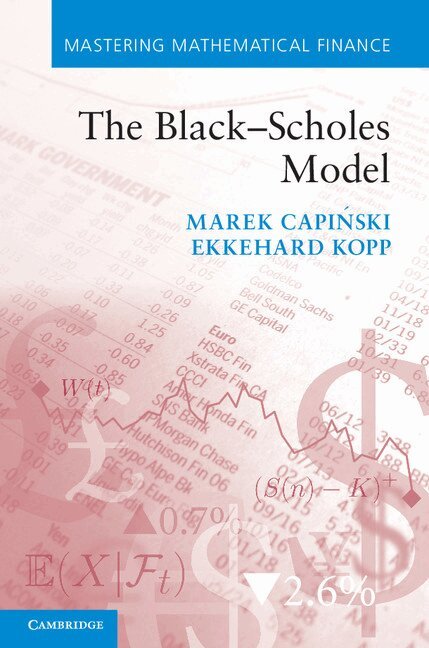
The Black-Scholes Model
Av Marek Capiński, Ekkehard Kopp
Häftad, 2012
687 kr
Lägg i varukorg
The Black-Scholes option pricing model is the first and by far the best-known continuous-time mathematical model used in mathematical finance. Here, it provides a sufficiently complex, yet tractable, testbed for exploring the basic methodology of option pricing. The discussion of extended markets, …
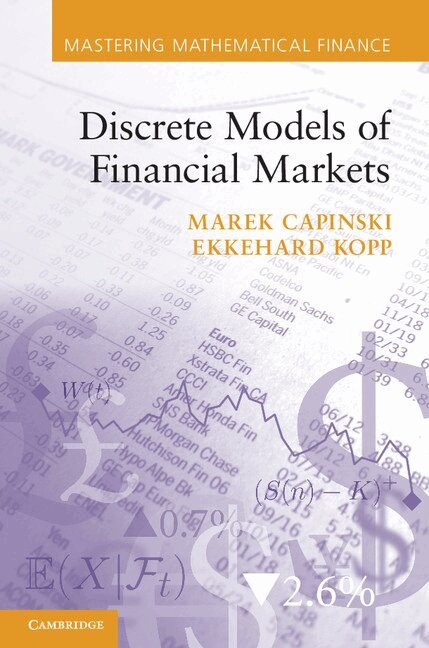
Discrete Models of Financial Markets
Av Marek Capiński, Ekkehard Kopp
Häftad, 2012
667 kr
Lägg i varukorg
This book explains in simple settings the fundamental ideas of financial market modelling and derivative pricing, using the no-arbitrage principle. Relatively elementary mathematics leads to powerful notions and techniques - such as viability, completeness, self-financing and replicating …
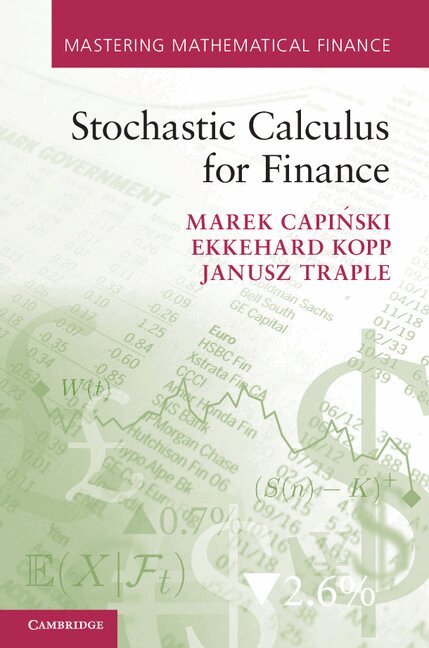
Stochastic Calculus for Finance
Av Marek Capiński, Ekkehard Kopp m. fl.
Häftad, 2012
667 kr
Lägg i varukorg
This book focuses specifically on the key results in stochastic processes that have become essential for finance practitioners to understand. The authors study the Wiener process and Itô integrals in some detail, with a focus on results needed for the Black-Scholes option pricing model. After …
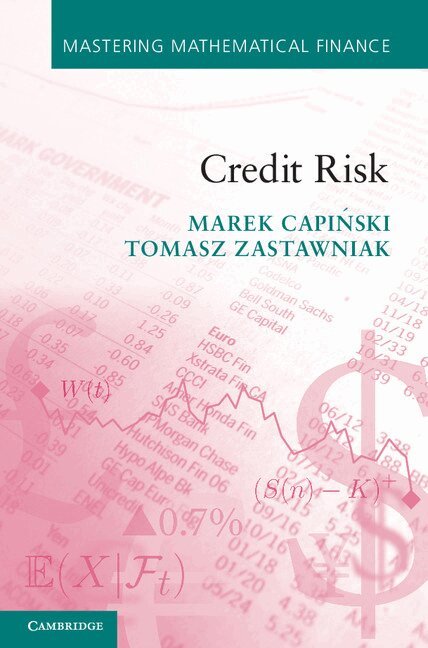
Credit Risk
Av Marek Capiński, Tomasz Zastawniak
Häftad, 2016
667 kr
Lägg i varukorg
Modelling credit risk accurately is central to the practice of mathematical finance. The majority of available texts are aimed at an advanced level, and are more suitable for PhD students and researchers. This volume of the Mastering Mathematical Finance series addresses the need for a course …
The Black-Scholes Model
Av Marek Capiński, Ekkehard Kopp
Inbunden, 2012
944 kr
Lägg i varukorg
The Black-Scholes option pricing model is the first and by far the best-known continuous-time mathematical model used in mathematical finance. Here, it provides a sufficiently complex, yet tractable, testbed for exploring the basic methodology of option pricing. The discussion of extended markets, …
Discrete Models of Financial Markets
Av Marek Capiński, Ekkehard Kopp
Inbunden, 2012
830 kr
Lägg i varukorg
This book explains in simple settings the fundamental ideas of financial market modelling and derivative pricing, using the no-arbitrage principle. Relatively elementary mathematics leads to powerful notions and techniques - such as viability, completeness, self-financing and replicating …
Stochastic Calculus for Finance
Av Marek Capiński, Ekkehard Kopp m. fl.
Inbunden, 2012
1051 kr
Lägg i varukorg
This book focuses specifically on the key results in stochastic processes that have become essential for finance practitioners to understand. The authors study the Wiener process and Itô integrals in some detail, with a focus on results needed for the Black-Scholes option pricing model. After …
Credit Risk
Av Marek Capiński, Tomasz Zastawniak
Inbunden, 2016
911 kr
Lägg i varukorg
Modelling credit risk accurately is central to the practice of mathematical finance. The majority of available texts are aimed at an advanced level, and are more suitable for PhD students and researchers. This volume of the Mastering Mathematical Finance series addresses the need for a course …