Chapman and Hall/CRC Financial Mathematics Series – serie
Visar alla böcker i serien Chapman and Hall/CRC Financial Mathematics Series. Handla med fri frakt och snabb leverans.
133 produkter
Financial Modelling with Jump Processes
Inbunden, 2003
2126 kr
Lägg i varukorg
WINNER of a Riskbook.com Best of 2004 Book Award!During the last decade, financial models based on jump processes have acquired increasing popularity in risk management and option pricing. Much has been published on the subject, but the technical nature of most papers makes them difficult for …
Introduction to Financial Mathematics
Option Valuation
Inbunden, 2019
2126 kr
Lägg i varukorg
Introduction to Financial Mathematics: Option Valuation, Second Edition is a well-rounded primer to the mathematics and models used in the valuation of financial derivatives. The book consists of fifteen chapters, the first ten of which develop option valuation techniques in discrete time, the last …
Risk Analysis in Finance and Insurance
Häftad, 2019
1069 kr
Lägg i varukorg
Risk Analysis in Finance and Insurance, Second Edition presents an accessible yet comprehensive introduction to the main concepts and methods that transform risk management into a quantitative science. Taking into account the interdisciplinary nature of risk analysis, the author discusses many …
Engineering BGM
Av Alan Brace
Häftad, 2019
1038 kr
Lägg i varukorg
Also known as the Libor market model, the Brace-Gatarek-Musiela (BGM) model is becoming an industry standard for pricing interest rate derivatives. Written by one of its developers, Engineering BGM builds progressively from simple to more sophisticated versions of the BGM model, offering a range of …
Structured Credit Portfolio Analysis, Baskets and CDOs
Av Christian Bluhm, Ludger Overbeck
Häftad, 2019
1069 kr
Lägg i varukorg
The financial industry is swamped by credit products whose economic performance is linked to the performance of some underlying portfolio of credit-risky instruments, like loans, bonds, swaps, or asset-backed securities. Financial institutions continuously use these products for tailor-made long …
American-Style Derivatives
Valuation and Computation
Häftad, 2019
994 kr
Lägg i varukorg
While the valuation of standard American option contracts has now achieved a fair degree of maturity, much work remains to be done regarding the new contractual forms that are constantly emerging in response to evolving economic conditions and regulations. Focusing on recent developments in the …
Financial Modelling in Commodity Markets
Häftad, 2019
805 kr
Lägg i varukorg
Financial Modelling in Commodity Markets provides a basic and self-contained introduction to the ideas underpinning financial modelling of products in commodity markets. The book offers a concise and operational vision of the main models used to represent, assess and simulate real assets and …
Machine Learning for Factor Investing: R Version
Av Guillaume Coqueret, Tony Guida
Inbunden, 2020
3055 kr
Lägg i varukorg
Machine learning (ML) is progressively reshaping the fields of quantitative finance and algorithmic trading. ML tools are increasingly adopted by hedge funds and asset managers, notably for alpha signal generation and stocks selection. The technicality of the subject can make it hard for …
Optional Processes
Theory and Applications
Av Mohamed Abdelghani, Alexander Melnikov
Häftad, 2022
791 kr
Lägg i varukorg
It is well-known that modern stochastic calculus has been exhaustively developed under usual conditions. Despite such a well-developed theory, there is evidence to suggest that these very convenient technical conditions cannot necessarily be fulfilled in real-world applications.Optional Processes: …
Machine Learning for Factor Investing: R Version
Av Guillaume Coqueret, Tony Guida
Häftad, 2020
1168 kr
Lägg i varukorg
Machine learning (ML) is progressively reshaping the fields of quantitative finance and algorithmic trading. ML tools are increasingly adopted by hedge funds and asset managers, notably for alpha signal generation and stocks selection. The technicality of the subject can make it hard for …
Machine Learning for Factor Investing
Python Version
Av Guillaume Coqueret, Tony Guida
Häftad, 2023
1110 kr
Lägg i varukorg
Machine learning (ML) is progressively reshaping the fields of quantitative finance and algorithmic trading. ML tools are increasingly adopted by hedge funds and asset managers, notably for alpha signal generation and stocks selection. The technicality of the subject can make it hard for …
Machine Learning for Factor Investing
Python Version
Av Guillaume Coqueret, Tony Guida
Inbunden, 2023
3055 kr
Lägg i varukorg
Machine learning (ML) is progressively reshaping the fields of quantitative finance and algorithmic trading. ML tools are increasingly adopted by hedge funds and asset managers, notably for alpha signal generation and stocks selection. The technicality of the subject can make it hard for …
Interest Rate Modeling
Theory and Practice, Second Edition
Av Lixin Wu
Häftad, 2020
617 kr
Lägg i varukorg
Containing many results that are new or exist only in recent research articles, Interest Rate Modeling: Theory and Practice portrays the theory of interest rate modeling as a three-dimensional object of finance, mathematics, and computation.
High-Performance Computing in Finance
Problems, Methods, and Solutions
Av M. A. H. Dempster, Juho Kanniainen m. fl.
Häftad, 2020
863 kr
Lägg i varukorg
High-Performance Computing (HPC) delivers higher computational performance to solve problems in science, engineering and finance. There are various HPC resources available for different needs, ranging from cloud computing– that can be used without much expertise and expense – to more tailored …
Equity-Linked Life Insurance
Partial Hedging Methods
Av Alexander Melnikov, Amir Nosrati
Häftad, 2020
791 kr
Lägg i varukorg
This book focuses on the application of the partial hedging approach from modern math finance to equity-linked life insurance contracts. It provides an accessible, up-to-date introduction to quantifying financial and insurance risks. The book also explains how to price innovative financial and …
Model-free Hedging
A Martingale Optimal Transport Viewpoint
Häftad, 2020
820 kr
Lägg i varukorg
Model-free Hedging: A Martingale Optimal Transport Viewpoint focuses on the computation of model-independent bounds for exotic options consistent with market prices of liquid instruments such as Vanilla options. The author gives an overview of Martingale Optimal Transport, highlighting the …
Portfolio Rebalancing
Häftad, 2020
791 kr
Lägg i varukorg
The goal of Portfolio Rebalancing is to provide mathematical and empirical analysis of the effects of portfolio rebalancing on portfolio returns and risks. The mathematical analysis answers the question of when and why fixed-weight portfolios might outperform buy-and-hold portfolios based on …
Derivative Pricing
A Problem-Based Primer
Av Ambrose Lo
Häftad, 2020
704 kr
Lägg i varukorg
The proliferation of financial derivatives over the past decades, options in particular, has underscored the increasing importance of derivative pricing literacy among students, researchers, and practitioners. Derivative Pricing: A Problem-Based Primer demystifies the essential derivative pricing …
Introduction to Computational Risk Management of Equity-Linked Insurance
Av Runhuan Feng
Häftad, 2020
805 kr
Lägg i varukorg
The quantitative modeling of complex systems of interacting risks is a fairly recent development in the financial and insurance industries. Over the past decades, there has been tremendous innovation and development in the actuarial field. In addition to undertaking mortality and longevity risks in …
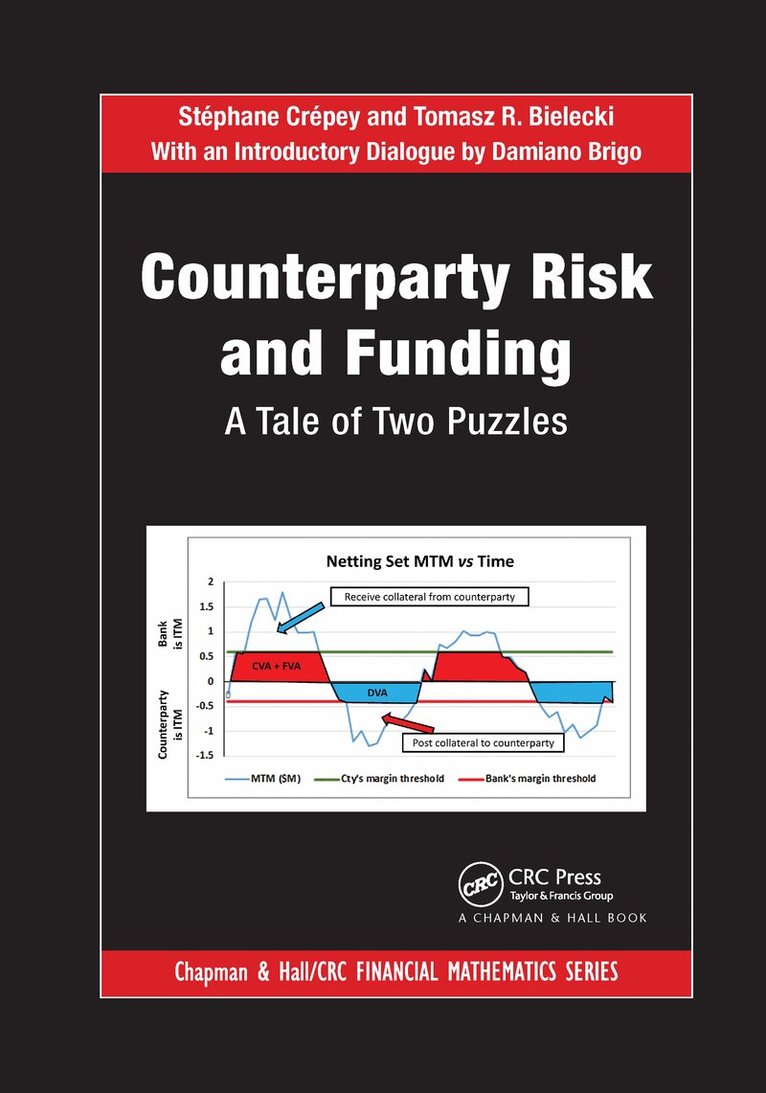
Counterparty Risk and Funding
A Tale of Two Puzzles
Av Stéphane Crépey, Tomasz R. Bielecki m. fl.
Häftad, 2020
791 kr
Lägg i varukorg
Solve the DVA/FVA Overlap Issue and Effectively Manage Portfolio Credit RiskCounterparty Risk and Funding: A Tale of Two Puzzles explains how to study risk embedded in financial transactions between the bank and its counterparty. The authors provide an analytical basis for the quantitative …
Risk Measures and Insurance Solvency Benchmarks
Fixed-Probability Levels in Renewal Risk Models
Inbunden, 2021
2126 kr
Lägg i varukorg
Risk Measures and Insurance Solvency Benchmarks: Fixed-Probability Levels in Renewal Risk Models is written for academics and practitioners who are concerned about potential weaknesses of the Solvency II regulatory system. It is also intended for readers who are interested in pure and applied …
Risk Measures and Insurance Solvency Benchmarks
Fixed-Probability Levels in Renewal Risk Models
Häftad, 2023
762 kr
Lägg i varukorg
Risk Measures and Insurance Solvency Benchmarks: Fixed-Probability Levels in Renewal Risk Models is written for academics and practitioners who are concerned about potential weaknesses of the Solvency II regulatory system. It is also intended for readers who are interested in pure and applied …
Metamodeling for Variable Annuities
Av Guojun Gan, Emiliano A. Valdez
Häftad, 2021
829 kr
Lägg i varukorg
This book is devoted to the mathematical methods of metamodeling that can be used to speed up the valuation of large portfolios of variable annuities. It is suitable for advanced undergraduate students, graduate students, and practitioners. It is the goal of this book to describe the computational …
Metamodeling for Variable Annuities
Av Guojun Gan, Emiliano A. Valdez
Inbunden, 2019
1562 kr
Lägg i varukorg
This book is devoted to the mathematical methods of metamodeling that can be used to speed up the valuation of large portfolios of variable annuities. It is suitable for advanced undergraduate students, graduate students, and practitioners. It is the goal of this book to describe the computational …
Introductory Mathematical Analysis for Quantitative Finance
Av Daniele Ritelli, Giulia Spaletta
Inbunden, 2020
2126 kr
Lägg i varukorg
Introductory Mathematical Analysis for Quantitative Finance is a textbook designed to enable students with little knowledge of mathematical analysis to fully engage with modern quantitative finance. A basic understanding of dimensional Calculus and Linear Algebra is assumed. The exposition of the …
Quantitative Finance with Python
A Practical Guide to Investment Management, Trading, and Financial Engineering
Inbunden, 2022
1876 kr
Lägg i varukorg
Quantitative Finance with Python: A Practical Guide to Investment Management, Trading and Financial Engineering bridges the gap between the theory of mathematical finance and the practical applications of these concepts for derivative pricing and portfolio management. The book provides students …
Financial Mathematics
A Comprehensive Treatment in Discrete Time
Av Giuseppe Campolieti, Roman N. Makarov
Häftad, 2024
878 kr
Lägg i varukorg
The book has been tested and refined through years of classroom teaching experience. With an abundance of examples, problems, and fully worked out solutions, the text introduces the financial theory and relevant mathematical methods in a mathematically rigorous yet engaging way.This textbook …
Sustainable Life Insurance
Managing Risk Appetite for Insurance Savings and Retirement Products
Av Aymeric Kalife, Ludovic Goudenège m. fl.
Inbunden, 2023
1827 kr
Lägg i varukorg
Sustainable Life Insurance: Managing Risk Appetite for Insurance Savings and Retirement Products gives an overview of all relevant aspects of traditional and non-traditional savings and retirement products from both insurers’ and policyholders’ respective risk appetites. Examples of such products …
C++ for Financial Mathematics
Häftad, 2021
808 kr
Lägg i varukorg
If you know a little bit about financial mathematics but don’t yet know a lot about programming, then C++ for Financial Mathematics is for you.C++ is an essential skill for many jobs in quantitative finance, but learning it can be a daunting prospect. This book gathers together everything you need …
Foundations of Quantitative Finance, Book I: Measure Spaces and Measurable Functions
Häftad, 2022
1216 kr
Lägg i varukorg
This is the first in a set of 10 books written for professionals in quantitative finance. These books fill the gap between informal mathematical developments found in introductory materials, and more advanced treatments that summarize without formally developing the important foundational results …