Häftad, Engelska, 2010
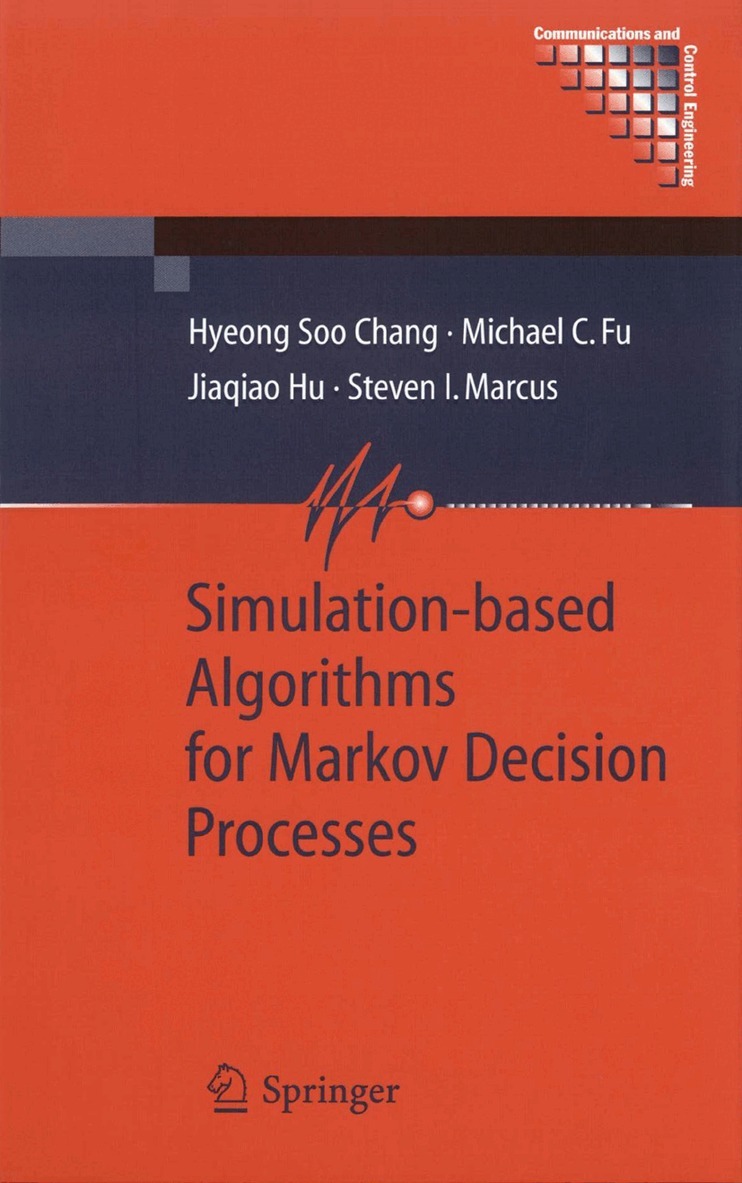
Simulation-based Algorithms for Markov Decision Processes
Av Hyeong Soo Chang, Michael C. Fu, Jiaqiao Hu, Steven I. Marcus
1521 kr
Tillfälligt slut
Beskrivning
Often, real-world problems modeled by Markov decision processes (MDPs) are difficult to solve in practise because of the curse of dimensionality. In others, explicit specification of the MDP model parameters is not feasible, but simulation samples are available. For these settings, various sampling and population-based numerical algorithms for computing an optimal solution in terms of a policy and/or value function have been developed recently. Here, this state-of-the-art research is brought together in a way that makes it accessible to researchers of varying interests and backgrounds. Many specific algorithms, illustrative numerical examples and rigorous theoretical convergence results are provided. The algorithms differ from the successful computational methods for solving MDPs based on neuro-dynamic programming or reinforcement learning. The algorithms can be combined with approximate dynamic programming methods that reduce the size of the state space and ameliorate the effects of dimensionality.
Produktinformation
- Utgivningsdatum: 2010-10-19
- Mått: 155 x 235 x undefined mm
- Vikt: 324 g
- Format: Häftad
- Språk: Engelska
- Serie: Communications and Control Engineering
- Antal sidor: 189
- Förlag: Springer London Ltd
- ISBN: 9781849966436
Utforska kategorier
Betyg & recensioner
0 recensioner
Inga recensioner tillgängliga.