Häftad, Engelska, 2004
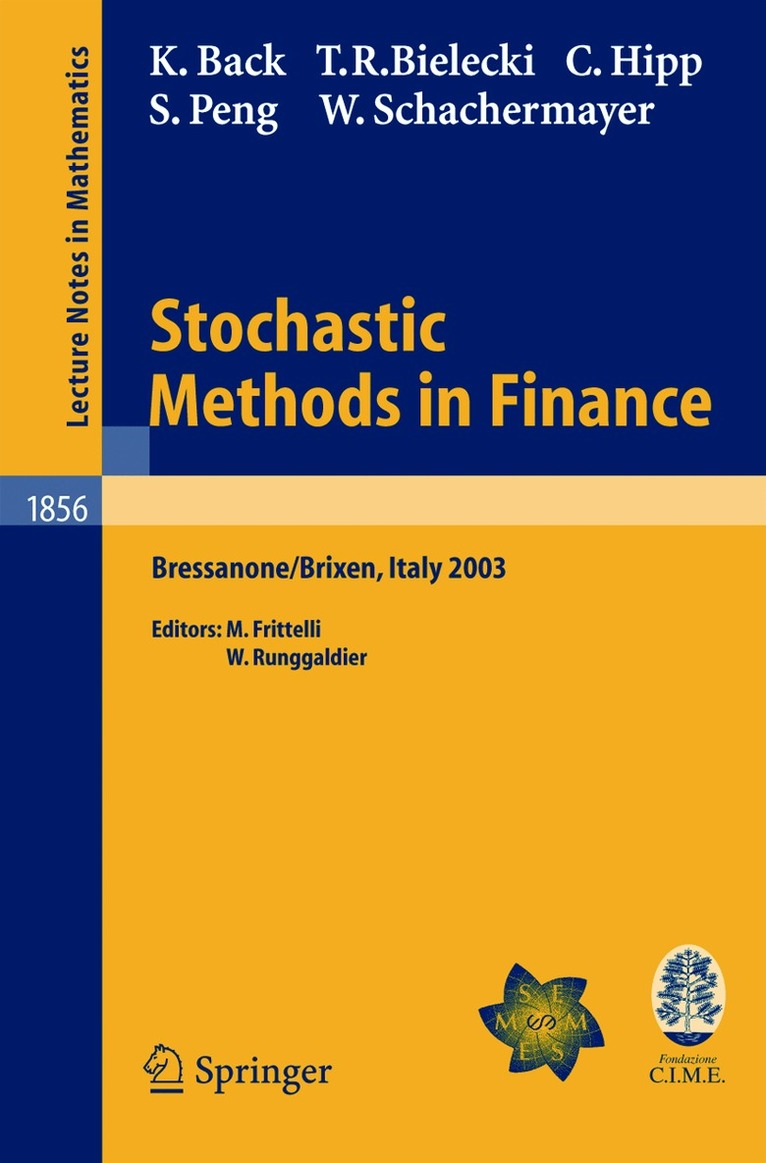
Stochastic Methods in Finance
Lectures given at the C.I.M.E.-E.M.S. Summer School held in Bressanone/Brixen, Italy, July 6-12, 2003
Av Kerry Back, Tomasz R. Bielecki, Christian Hipp, Shige Peng, Walter Schachermayer, Marco Frittelli, Wolfgang J. Runggaldier
551 kr
Beställningsvara. Skickas inom 10-15 vardagar. Fri frakt över 249 kr.
Beskrivning
This volume includes the five lecture courses given at the CIME-EMS School on "Stochastic Methods in Finance" held in Bressanone/Brixen, Italy 2003. It deals with innovative methods, mainly from stochastic analysis, that play a fundamental role in the mathematical modelling of finance and insurance: the theory of stochastic processes, optimal and stochastic control, stochastic differential equations, convex analysis and duality theory. Five topics are treated in detail: Utility maximization in incomplete markets; the theory of nonlinear expectations and its relationship with the theory of risk measures in a dynamic setting; credit risk modelling; the interplay between finance and insurance; incomplete information in the context of economic equilibrium and insider trading.
Produktinformation
- Utgivningsdatum: 2004-11-22
- Mått: 155 x 235 x undefined mm
- Format: Häftad
- Språk: Engelska
- Serie: Lecture Notes in Mathematics
- Antal sidor: 312
- Förlag: Springer-Verlag Berlin and Heidelberg GmbH & Co. KG
- ISBN: 9783540229537
Utforska kategorier
Betyg & recensioner
0 recensioner
Inga recensioner tillgängliga.