Sabrina Mulinacci – författare
Visar alla böcker från författaren Sabrina Mulinacci. Handla med fri frakt och snabb leverans.
10 produkter
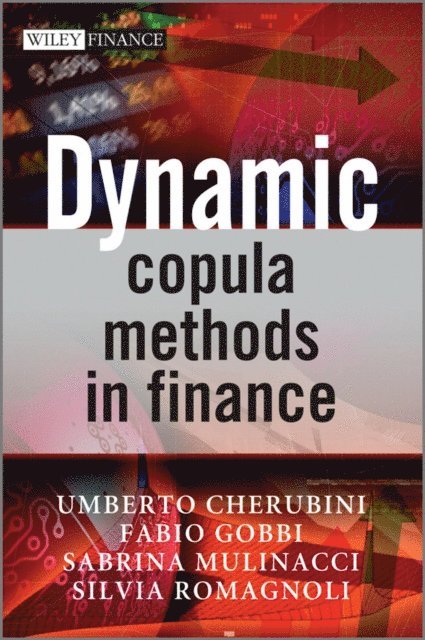
Dynamic Copula Methods in Finance
Av Umberto Cherubini, Sabrina Mulinacci m. fl.
Inbunden, 2011
1041 kr
Lägg i varukorg
The latest tools and techniques for pricing and risk managementThis book introduces readers to the use of copula functions to represent the dynamics of financial assets and risk factors, integrated temporal and cross-section applications. The first part of the book will briefly introduce the …
Fourier Transform Methods in Finance
Av Pietro Rossi, Sabrina Mulinacci m. fl.
E-bok, 2010
1340 kr
Lägg i varukorg
In recent years, Fourier transform methods have emerged as one of the major methodologies for the evaluation of derivative contracts, largely due to the need to strike a balance between the extension of existing pricing models beyond the traditional Black - Scholes setting and a need to evaluate …
Fourier Transform Methods in Finance
Av Pietro Rossi, Sabrina Mulinacci m. fl.
E-bok, 2010
1369 kr
Lägg i varukorg
In recent years, Fourier transform methods have emerged as one of the major methodologies for the evaluation of derivative contracts, largely due to the need to strike a balance between the extension of existing pricing models beyond the traditional Black - Scholes setting and a need to evaluate …
Dynamic Copula Methods in Finance
Av Silvia Romagnoli, Fabio Gobbi m. fl.
E-bok, 2011
1212 kr
Lägg i varukorg
The latest tools and techniques for pricing and risk management This book introduces readers to the use of copula functions to represent the dynamics of financial assets and risk factors, integrated temporal and cross-section applications. The first part of the book will briefly introduce the …
Marshall Olkin Distributions - Advances in Theory and Applications
Bologna, Italy, October 2013
Av Umberto Cherubini, Fabrizio Durante m. fl.
Inbunden, 2015
1096 kr
Lägg i varukorg
This book presents the latest advances in the theory and practice of Marshall-Olkin distributions. These distributions have been increasingly applied in statistical practice in recent years, as they make it possible to describe interesting features of stochastic models like non-exchangeability, …
Marshall Olkin Distributions - Advances in Theory and Applications
Bologna, Italy, October 2013
Av Sabrina Mulinacci, Fabrizio Durante m. fl.
E-bok, 2015
1427 kr
Lägg i varukorg
This book presents the latest advances in the theory and practice of Marshall-Olkin distributions. These distributions have been increasingly applied in statistical practice in recent years, as they make it possible to describe interesting features of stochastic models like non-exchangeability, …
Marshall Olkin Distributions - Advances in Theory and Applications
Bologna, Italy, October 2013
Av Umberto Cherubini, Fabrizio Durante m. fl.
Häftad, 2016
1096 kr
Lägg i varukorg
This book presents the latest advances in the theory and practice of Marshall-Olkin distributions. These distributions have been increasingly applied in statistical practice in recent years, as they make it possible to describe interesting features of stochastic models like non-exchangeability, …
Convolution Copula Econometrics
Av Umberto Cherubini, Fabio Gobbi m. fl.
Häftad, 2016
606 kr
Lägg i varukorg
This book presents a novel approach to time series econometrics, which studies the behavior of nonlinear stochastic processes. This approach allows for an arbitrary dependence structure in the increments and provides a generalization with respect to the standard linear independent increments …
Convolution Copula Econometrics
Av Sabrina Mulinacci, Fabio Gobbi m. fl.
E-bok, 2016
797 kr
Lägg i varukorg
This book presents a novel approach to time series econometrics, which studies the behavior of nonlinear stochastic processes. This approach allows for an arbitrary dependence structure in the increments and provides a generalization with respect to the standard linear independent increments …