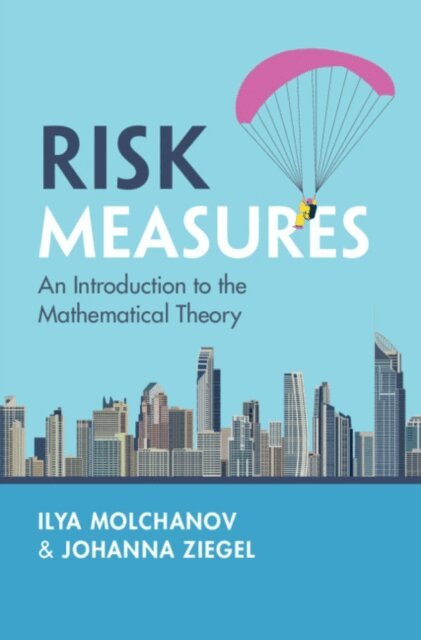
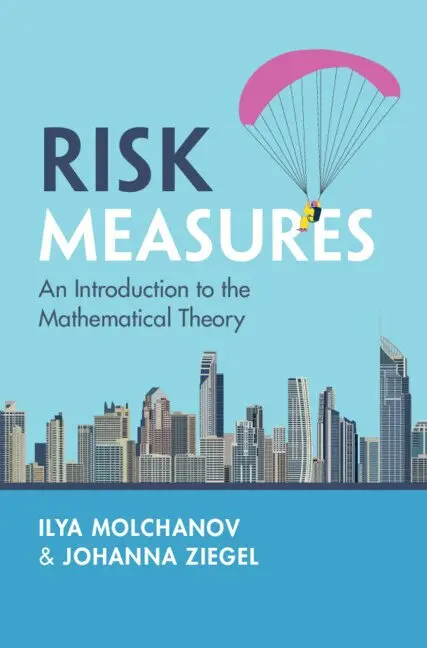
Risk Measures
An Introduction to the Mathematical Theory
AvIlya Molchanov,Johanna Ziegel
456 kr
Skickas . Fri frakt över 249 kr.
Du är på sajten för privatpersoner.
AvIlya Molchanov,Johanna Ziegel
456 kr
Skickas . Fri frakt över 249 kr.
Ilya Molchanov is Professor of Probability at the University of Bern, having previously worked at the University of Glasgow. He specialises in stochastic geometry. He authored 'Theory of Random Sets' (2017) and co-authored 'Random Sets in Econometrics' (2018) with Francesca Molinari, discussing the econometric applications of his work at the interface between probability theory and convex geometry. Johanna Ziegel is Professor of Statistics at ETH Zurich, having previously worked at the University of Bern. Her expertise is statistical forecasting theory and applications, mainly in finance and meteorology.
'This book presents the one period theory of risk measurement or monetary utility functions. Since their introduction in the nineties, the theory and its applications have undergone a lot of changes. It is the right time to compile the advances in a new book. To benefit fully, the reader should follow the advice of Paul Halmos: to learn mathematics you must do mathematics and therefore should certainly solve the numerous exercises that accompany every chapter. Some of them are trivial, but not easy; some are intermediate. The last chapter puts emphasis on multivalued risk measurement which is a new development. The reader (solving the exercises) will learn a lot when studying this book.' Freddy Delbaen, ETH Zurich
Du är på sajten för privatpersoner.
AvIlya Molchanov,Johanna Ziegel
456 kr
Skickas . Fri frakt över 249 kr.
Ilya Molchanov is Professor of Probability at the University of Bern, having previously worked at the University of Glasgow. He specialises in stochastic geometry. He authored 'Theory of Random Sets' (2017) and co-authored 'Random Sets in Econometrics' (2018) with Francesca Molinari, discussing the econometric applications of his work at the interface between probability theory and convex geometry. Johanna Ziegel is Professor of Statistics at ETH Zurich, having previously worked at the University of Bern. Her expertise is statistical forecasting theory and applications, mainly in finance and meteorology.
'This book presents the one period theory of risk measurement or monetary utility functions. Since their introduction in the nineties, the theory and its applications have undergone a lot of changes. It is the right time to compile the advances in a new book. To benefit fully, the reader should follow the advice of Paul Halmos: to learn mathematics you must do mathematics and therefore should certainly solve the numerous exercises that accompany every chapter. Some of them are trivial, but not easy; some are intermediate. The last chapter puts emphasis on multivalued risk measurement which is a new development. The reader (solving the exercises) will learn a lot when studying this book.' Freddy Delbaen, ETH Zurich